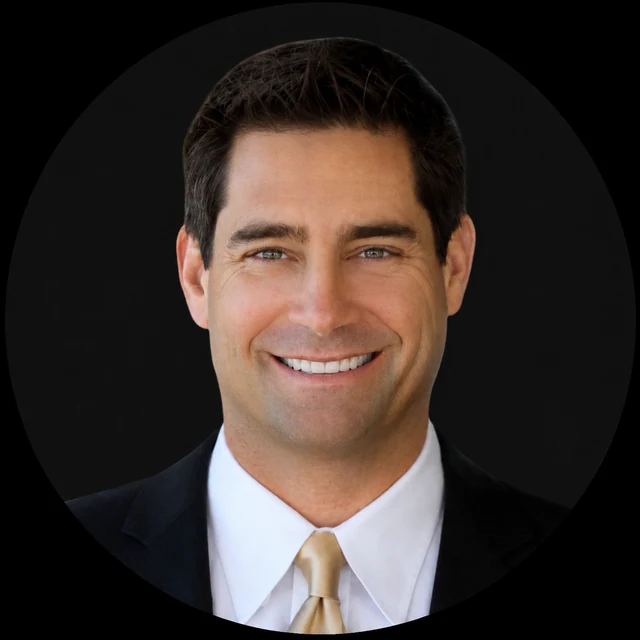
Foundation Dental Faculty
Matt Ornstein
Co-Founder and Co-CEO, Dental Pitch Brokerage | Co-CEO, Fortem Holdings | Co-Owner, Oak Dental Partners | Author
Foundation Dental Alliance Faculty | Practice Value, EBITDA, and Transitions
Matt Ornstein is a business owner, investor, author, and dental M&A advisor who helped build Oak Dental Partners from 20 offices into an organization with more than 80 locations across nine states. After years of acquiring, financing, and governing dental practices, he co-founded Dental Pitch Brokerage to represent dentists preparing to sell.
He came to dental transitions from the buyer's side of the table, and that's what separates him from almost everyone advising sellers today. Most brokers have never underwritten an acquisition. Ornstein has done it repeatedly with institutional capital at risk, and he knows the exact mental model a sophisticated buyer applies when they open a practice's financials. He built Dental Pitch because too many dentists were selling practices they'd spent a career building to buyers who were far better prepared for the transaction than they were.
As Foundation Dental Alliance faculty, Ornstein teaches practice owners how value is actually created and destroyed in the years before a sale. His work covers EBITDA and valuation mechanics, owner dependence, financial documentation, deal structure, buyer psychology, and why the best preparation starts 12 to 36 months before anything goes to market.
From Real Estate to Dental Ownership
Ornstein earned his Bachelor of Science in Commerce from the University of Virginia's McIntire School of Commerce in 1990 and began his career with The Home Depot, where he learned large-format operations inside one of the most demanding retail environments in the country. He wasn't studying efficiency in a classroom. He was running it.
In 1996 he left to found an Atlanta-based real estate development company. His early multifamily projects won multiple first-place awards from the Greater Atlanta Homebuilders Association, and he delivered double-digit annualized returns to his investors. The discipline behind it was simple. He bought right, managed well, and sold at full value.
In 2002 he co-founded The Ornstein-Schuler Companies with Frank Schuler IV. His work there covered the acquisition, due diligence, development, rezoning, and disposition of several hundred million dollars in real estate across multiple states, including more than 100 property re-zonings. A rezoning isn't a paperwork exercise. It's a negotiation with city councils, planning boards, and competing interests, which makes it a long lesson in patience and knowing when to push.
That background shaped how he approaches dental organizations today. He studies the underlying economics of a business, the risks a buyer will uncover in diligence, and the systems an organization needs in order to keep performing without depending on a single owner.
Building Oak Dental Partners
Ornstein co-founded Fortem Holdings, a private equity firm, in 2020. Through Fortem he helped acquire Children and Teen Dental Group, which became Oak Dental Partners after a March 2021 recapitalization managed by Houlihan Lokey brought Fortem in as controlling sponsor. He wasn't an outside investor who hired a management team and went home. He was in it, learning what it takes to integrate more than 80 practices without losing the clinical culture that made them worth acquiring in the first place.
From 20 dental offices with $7,000,000 in EBITDA to 60 dental offices with over $20,000,000 in EBITDA in three years.
Matt Ornstein, The Dental EBITDA Handbook
Oak today includes more than 80 locations across Georgia, Florida, Alabama, Pennsylvania, South Carolina, North Carolina, Texas, Virginia, and Mississippi, providing pediatric dentistry, family dentistry, orthodontics, and oral surgery. Its practices collectively serve roughly 250,000 patients each year and generate more than $100 million in annual collections, with an enterprise value exceeding $275 million.
The capital behind it is institutional. Comvest Credit Partners provided a $105 million term loan, a $43 million delayed-draw term loan, and a revolver in May 2023, with Catalur Capital contributing $35 million of structured preferred equity and B. Riley Financial advising. PitchBook data reports approximately $302 million in total institutional capital raised across Oak's funding history. Those are capital markets events that require audited financials, lender due diligence, and proven operating performance.
Ornstein serves at the ownership and board level while Oak's leadership team runs daily operations. That seat gives him direct insight into how dental organizations evaluate acquisitions, allocate capital, manage risk, and judge whether a practice will keep performing after the selling dentist steps away.
Helping Dentists Prepare for a Sale
In June 2023, Ornstein co-founded Dental Pitch Brokerage with Elijah Desmond, the dental hygienist turned entrepreneur behind Smiles at Sea and The Dental Festival. The firm's positioning is explicit and it doesn't bend. Dental Pitch represents sellers only, accepts no buyer-side engagements, and takes no dual-agency listings.
- The live pitch event. Rather than quietly sending a one-page teaser to a shortlist of buyers and waiting for offers to trickle in, Dental Pitch stages in-person pitch events at major dental conferences where a selling dentist presents to roughly ten qualified buyers at once. The format lets a seller compare financial offers, deal terms, cultural alignment, and post-sale expectations before choosing a partner.
- Aligned economics. No upfront fees and no engagement retainer. Dental Pitch gets paid when the deal closes, and legal support runs through Dykema so sellers don't carry separate legal costs until a letter of intent is signed.
- An advisory board with real weight. Dykema's Brian Colao, one of the most recognized DSO attorneys in the country, sits alongside ADSO co-founders Doug Brown and Mitch Olan. The team has collectively supported more than $200 million in dental practice sales.
Ornstein teaches dentists to begin preparing 12 to 36 months before entering the market. The work focuses on improving EBITDA, cleaning up financial reporting, strengthening hygiene production, documenting operating systems, reducing owner dependence, and understanding how buyers evaluate risk. He also helps owners assess the parts of an offer that sit beyond the headline price, including rollover equity, earnouts, employment obligations, control provisions, and how likely the projected proceeds are to actually be realized.
The EBITDA-First Framework
Every conversation Ornstein has with a practice owner starts in the same place. Buyers don't buy collections. They buy risk, predictability, and cash flow.
Net income is close to irrelevant for valuation purposes. Two practices with identical EBITDA can carry wildly different net income profiles and still command the same price, because buyers are underwriting EBITDA rather than the owner's personal cash flow. Once a dentist internalizes that, they start running the practice differently, years before they ever plan to sell.
He breaks the market into two valuation worlds. Below roughly $10 million in collections, practices are typically valued as a percentage of collections, somewhere between 80 and 120 percent depending on specialty, location, payer mix, and transferability. Above that threshold, buyers shift to EBITDA multiples and the math changes entirely. Every additional $100,000 of EBITDA at a seven times multiple adds $700,000 to the sale price, which is why he treats EBITDA improvement as the highest-return investment an owner can make in their own business. A well-run practice should net 20 to 30 percent of collections as EBITDA. Most don't, and that gap is the real preparation work.
- What moves the multiple up. Low owner dependence, strong recurring hygiene production, clean financial ledgers with defensible add-backs, multi-specialty integration, and properly implemented technology.
- What destroys value. Personal expenses buried in the profit and loss statement, underdocumented financials that create retrade opportunities in diligence, and burnout-driven timing.
His central advice to practice owners is direct.
Sell before burnout, not because of it.
Matt Ornstein
The owner who waits until they're exhausted almost always leaves money on the table, accepts terms they later regret, or discovers too late that the practice is more owner-dependent than any buyer will tolerate.
Books and Philanthropy
- The Dental EBITDA Handbook. Published July 31, 2024, co-authored with Dr. Catrise Austin. Roughly twenty pages dismantling the most persistent misconception in dental M&A, which is that buyers value practices on net income. It reached top-100 rankings in the Valuation category on Amazon Kindle.
- The Art of the Dental Deal. Published 2025, co-authored with Dr. Catrise Austin. Where the Handbook teaches the metric, this one teaches the strategy. Operations, profitability, pre-sale preparation, deal structure, earnout mechanics, rollover equity, and the human psychology of selling something you've spent a career building.
One hundred percent of the proceeds from both books supports financial assistance for underprivileged dental students in the United States, and both are available as free downloads. He didn't write them to monetize them. He wrote them to give the knowledge away.
His philanthropic work has also funded more than 60 full-ride scholarships for students from underserved backgrounds and more than 200 cleft lip and palate surgeries for children who couldn't otherwise access care. He has supported conservation projects protecting thousands of acres and endangered species habitat across the Southeast, along with animal rescue and rehabilitation efforts.
What runs through all of it is a consistent orientation. He builds things that last, then works to make sure other people get the benefit of them. His practice as a seller's advocate is the same instinct. He isn't trying to extract value from a dentist during a vulnerable moment. He's trying to make sure they don't leave decades of work on the table because nobody explained how the other side of the table thinks.
Faculty Focus
Ornstein's work with Foundation Dental Alliance covers:
- Dental practice valuation and EBITDA improvement
- DSO ownership, acquisitions, and growth strategy
- Preparing a practice 12 to 36 months before a sale
- Buyer psychology and acquisition due diligence
- Reducing owner dependence and increasing transferability
- Competitive buyer processes and seller representation
- Deal structure, rollover equity, earnouts, and post-sale risk
- Protecting a dentist's legacy during a practice transition
Ornstein doesn't arrive at the dental M&A table with theory. He arrives with receipts. He has spent years across the table from dental practice sellers with institutional capital at stake, and at Foundation Dental Alliance he uses that experience to help dentists prepare earlier, understand the buyer's financial perspective, and protect more of what they spent a career building.
Booking and Contact
- Base: Jacksonville, Florida, with primary business operations in the Atlanta metropolitan area
- Firms: Dental Pitch Brokerage, Fortem Holdings, Oak Dental Partners, The Ornstein-Schuler Companies
- Books: The Dental EBITDA Handbook and The Art of the Dental Deal
- Available for: Luxury Dental Retreats, Foundation Dental Mastermind implementation sessions, Foundation Dental Transitions guidance, keynote presentations, and Foundation Dental Podcast appearances